Florida law protects non-fault drivers from unfair rate increases, ensuring your insurance company cannot legally raise your rates just because another vehicle struck you.
Many drivers worry about how much their car insurance rates will go up with an at-fault accident or worry about financial penalties simply for reporting a collision to their carrier. When another driver's negligence causes physical harm and vehicle damage, seeking medical care and legal guidance helps shield your finances.
Reaching out to a knowledgeable Florida car accident attorney for a free case evaluation ensures your rights remain protected while you pursue recovery.
Key Takeaways: Car Insurance Increases After an Accident in FL
- Florida statute 626.9541 prohibits premium surcharges for accidents where you were not substantially at fault
- Mandated personal injury protection claims do not grant insurers authorization to raise personal rates
- Financial liability for increased premiums rests primarily on drivers assessed with partial or complete fault
- Incomplete crash reports and insurer fault disputes can cause incorrect premium surcharge rate calculations
- Strict legal filing deadlines apply for pursuing civil recovery against negligent drivers and government agencies
Will my car insurance go up if someone hits me in Florida?
Florida law prevents car insurance companies from raising your premium solely because you were involved in an accident that you did not cause.
- Insurers cannot add a surcharge or increase your monthly rate if the official crash record shows you were entirely free of fault.
- Using your own mandatory Personal Injury Protection benefits to pay for medical care after a non-fault collision does not trigger penalty rate hikes under state regulations.
- Submitting a third-party claim against the responsible driver's insurance policy has no direct negative impact on your personal policy standing.
State statutes explicitly protect non-fault drivers from unfair rate increases after a roadway collision.
Does Florida Law Allow Insurance Rate Increases for Non-Fault Collisions?
Florida law prohibits insurance companies from increasing your premium rates if you were not substantially at fault for a motor vehicle collision.
Florida Statute 626.9541 lays down strict guidelines regarding unfair insurance trade practices. Under this statute, insurance companies cannot legally apply a premium surcharge or cancel your policy simply because you were involved in an accident. This depends, of course, on whether the made a good faith determination that you were substantially at fault.
This protection applies whether you use your own Personal Injury Protection benefits or file a claim against the at-fault party.
What Standard Determines Fault for Insurance Rate Surcharges in Florida?
Insurance companies must establish clear evidence that you carried more than 50 percent of the responsibility for a crash before raising your rates.
Under Florida regulations, insurers look at law enforcement crash reports, physical vehicle damage patterns, and witness statements to assign fault percentages. If an insurance carrier tries to raise your rate without proving substantial fault, the company violates state insurance rules.
You hold the legal right to challenge unfair fault determinations made by insurance adjusters.
How Do Insurance Adjusters Assign Fault Percentages After a Highway Crash?
Adjusters analyze police reports, physical damage, and driver statements to calculate each party's percentage of fault.
Sometimes, insurance companies rush to assign shared fault to limit their financial exposure, claiming you were speeding or failing to pay attention. If an adjuster unfairly assigns you 20 or 30 percent of the blame, your rate might remain steady, but your ultimate payout from the other driver decreases under Florida modified comparative fault rules.
Having an attorney handle communications prevents insurance adjusters from twisting your words to assign unfair blame.
How Much Will My Insurance Go Up with an At-Fault Accident?
An at-fault accident in Florida typically increases auto insurance premiums by 30 to 50 percent annually, depending on your carrier and the severity of the crash.
If an insurer determines you caused a collision, your annual rate will likely rise significantly at your next policy renewal period. The exact dollar increase depends on factors like your past driving record, whether injuries occurred, and total property damage amounts.
Premium surcharges usually remain attached to your insurance profile for three to five years before dropping off.
How Does Claim Severity Impact Premium Increases After an At-Fault Crash?
Insurance carriers apply larger rate surcharges to claims that involve high medical costs and severe vehicle destruction.
When an at-fault crash leads to emergency room visits, ongoing physical therapy, or total vehicle losses, the insurer's total payout rises. High financial payouts translate directly into higher risk scores for the driver, leading insurers to charge higher rates to offset future loss risks.
Maintaining a clean driving record before an incident helps minimize the overall percentage spike.
How Does Using Personal Injury Protection Affect Your Insurance Premium?
Filing a Personal Injury Protection claim with your own insurance company does not allow your carrier to raise your monthly premium for a non-fault accident.
Florida requires all vehicle owners to carry $10,000 in PIP benefits to ensure rapid medical care access after crashes. Because Florida operates as a no-fault state, your own PIP policy pays your emergency room fees and medical bills first, even when another vehicle strikes you.
To learn more about how mandatory medical benefits function, reading about Florida's no-fault system helps clarify your legal rights.
What Happens When You Use PIP Coverage After a Crash?
Your insurance company pays 80 percent of reasonable medical bills up to your policy limit, regardless of who caused the collision.
Florida law mandates that using these statutory medical benefits after a crash caused by another driver cannot serve as the sole reason for a premium hike. Your insurer pays medical providers directly while your legal team works to recover remaining unpaid expenses from the negligent driver.
Can Using PIP Impact Your Policy Renewal Terms?
Using PIP benefits for a non-fault collision will not cause your insurance carrier to non-renew your policy or drop your coverage.
State regulations protect consumers who access the insurance coverage they pay for every month. As long as official records show another party caused the crash, your policy standing remains secure.
If your insurer attempts to non-renew your policy improperly, administrative complaints can be filed with state insurance regulators.
How Does Filing a Claim Against the At-Fault Driver Work in Florida?
Submitting a third-party claim against the responsible driver's insurance policy covers expenses that exceed your basic PIP limits without affecting your own rates.
When another driver's carelessness causes physical trauma, primary PIP limits of $10,000 often prove inadequate to cover hospital stays, ongoing therapy, and lost income. You must pursue a third-party liability claim against the negligent driver to recover additional financial losses.
Consulting a focused Clearwater car accident lawyer ensures your claim accounts for all past and future care costs. If your accident occurred in Hillsborough County, partnering with a skilled Tampa car accident lawyer helps you gather local crash reports and challenge aggressive insurance adjusters.
What Expenses Can You Recover from the At-Fault Driver's Insurance Policy?
A third-party liability claim allows you to pursue full financial recovery for expenses not covered by basic no-fault insurance benefits.
- Remaining Unpaid Medical Bills: The 20 percent of medical expenses and costs above PIP limits.
- Complete Lost Income: Full reimbursement for missed paychecks and lost future earning capacity.
- Physical Pain and Suffering: Compensation for physical discomfort, trauma, and reduced daily life enjoyment.
- Complete Property Damage: Total costs to repair or replace your damaged motor vehicle.
Why Does Pursuing a Third-Party Claim Protect Your Financial Standing?
Filing against the at-fault driver's policy places financial responsibility directly on the party who caused your injuries.
Your own insurance policy remains unaffected while your legal team negotiates with the negligent driver's commercial carrier. This approach ensures you receive full compensation for ongoing medical care without risking personal insurance surcharges.
What Steps Help Prevent Unfair Insurance Rate Increases After a Florida Collision?
Taking structured actions following an accident ensures clear evidence exists to prove you were not at fault for the crash.
Gathering proper documentation right away prevents insurance companies from improperly assigning blame to you. Injured individuals find it helpful to follow a systematic approach after a collision:
- Obtain a complete copy of the official police crash report to verify that law enforcement cited the other driver for traffic violations.
- Take detailed photos of vehicle positioning, skid marks, traffic signals, weather conditions, and physical injuries before leaving the crash scene.
- Collect contact information and written statements from independent witnesses who saw the collision occur.
- Notify your insurance carrier about the collision promptly, but explicitly state that you were not at fault.
- Maintain complete files of all medical records, doctor discharge forms, physical therapy schedules, and medical bills.
What Are the Legal Timelines for Filing a Car Accident Claim in Florida?
Florida law gives you two years from the crash date to file a personal injury lawsuit in civil court against a negligent private driver.
If you fail to file your lawsuit before the two-year deadline passes, Florida courts will dismiss your case permanently. Missing this cutoff removes all your bargaining leverage, leaving you unable to recover money for medical care or lost wages.
Starting your legal claim early gives your attorney time to gather fresh evidence and interview key witnesses.
What Special Deadlines Apply to Claims Against Florida Government Entities?
Claims involving government vehicles, city buses, or dangerous road conditions require serving a formal written notice within three years under Florida Statute 768.28.
If a city maintenance truck or a poorly designed municipal roadway caused your crash, strict sovereign immunity rules apply. You must submit a detailed notice of claim to the relevant agency and the Florida Department of Financial Services before filing a lawsuit in court.
The agency gets a mandatory 180-day investigation period to review your claim, requiring early preparation to meet all statutory requirements.
Why Is Having an Attorney Important for Handling Insurance Claims?
Insurance companies employ experienced adjusters and legal teams dedicated to minimizing payouts and assigning partial fault to injured drivers.
Having a knowledgeable attorney manage your claim levels the playing field against large insurance corporations. Your lawyer handles all written and verbal communications, preventing adjusters from twisting your words to justify rate surcharges or lower settlement offers.
Attorneys conduct independent investigations, review vehicle event data recorders, and consult accident reconstruction specialists to prove the other driver caused the crash.
Without legal representation, injured victims often face delayed payments, denied coverage, and unfair fault assignments that hurt their long-term recovery.
Frequently Asked Questions About Car Insurance Rates Increasing After a Florida Car Crash
Will my insurance rates go up if an uninsured driver hits my car in Florida?
No, your insurer cannot legally raise your rates solely because an uninsured driver struck your vehicle, provided you were not at fault. You can file a claim under your Uninsured Motorist coverage or PIP without facing statutory premium surcharges.
What should I do if my insurance company wrongfully increases my rate after a non-fault crash?
You should contact your insurer in writing, provide a copy of the official police report showing zero fault, and demand a rate correction. If the company refuses to remove the surcharge, you can file a formal administrative complaint with the Florida Office of Insurance Regulation.
Does using my roadside assistance or towing coverage trigger a premium rate hike?
Using roadside assistance or towing benefits does not generally cause a major premium increase, but some insurers count service calls as policy claims. Frequent roadside assistance claims within a short window can sometimes lead an insurer to non-renew optional towing add-ons upon policy renewal.
Can my insurance company drop my coverage after an at-fault accident in Florida?
Yes, an insurance company can choose not to renew your policy upon expiration if an at-fault crash involves gross negligence, reckless driving, or a DUI conviction. Insurers must provide written notice at least 45 days before the non-renewal date under Florida law.
How does my insurance go up with an at-fault accident change if I have accident forgiveness?
Accident forgiveness prevents your insurance premium from rising after your first at-fault collision, provided you purchased the endorsement before the incident. However, the crash still appears on your driving record and will impact rates if you switch insurance carriers later.
Schedule a Free Consultation with Roman Austin Car Accident and Personal Injury Lawyers
If another driver's negligence left you injured in a vehicle collision in Florida, do not let insurance carriers take advantage of your situation or assign unfair blame. Our legal team understands how insurance companies operate, and we stand ready to protect your rights, challenge unfair rate hikes, and fight for full financial compensation.
Contact Roman Austin Car Accident and Personal Injury Lawyers anytime 24/7 at (727) 787-2500 for a free case evaluation with an experienced attorney.
Roman Austin Car Accident and Personal Injury Lawyers: 1811 N Belcher Rd, Suite I-1, Clearwater, FL 33765
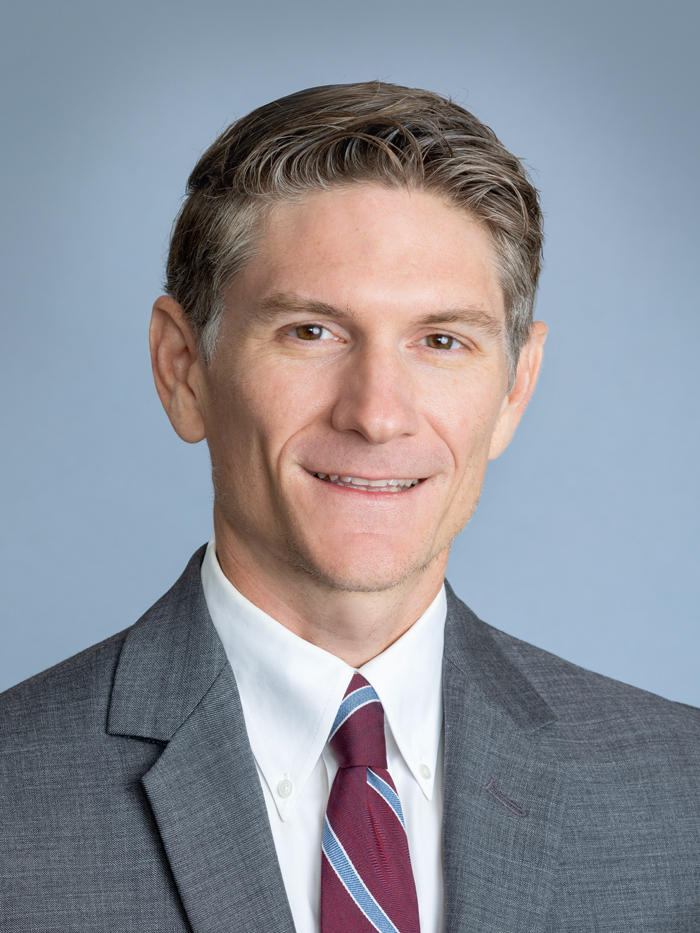
John C. Austin
Partner and Trial Attorney
John C. Austin spent twelve years defending insurance companies, first at a Florida defense firm and then in-house at State Farm, before turning that experience toward injured clients. He holds the CPCU designation, earned by fewer than 4% of the insurance industry. A St. Petersburg native and University of Florida law graduate, he has handled thousands of personal injury claims and tried cases to verdict as first chair.
Author's Bio

