Florida is a no-fault state, but that label misleads a lot of people. No-fault doesn't mean nobody is to blame. It means your own PIP insurance in Florida pays your first medical bills and lost income, no matter who caused the crash, while the at-fault driver still answers for losses beyond PIP.
If another driver hurt you, that distinction matters right away. PIP runs out quickly after a serious crash, and the 14-day treatment deadline catches people who try to tough out their pain at home. Meanwhile, the bills keep coming.
A Florida car accident attorney can explain where your PIP ends and a claim against the at-fault driver begins. A free consultation gives you those answers before you sign anything or give a recorded statement.
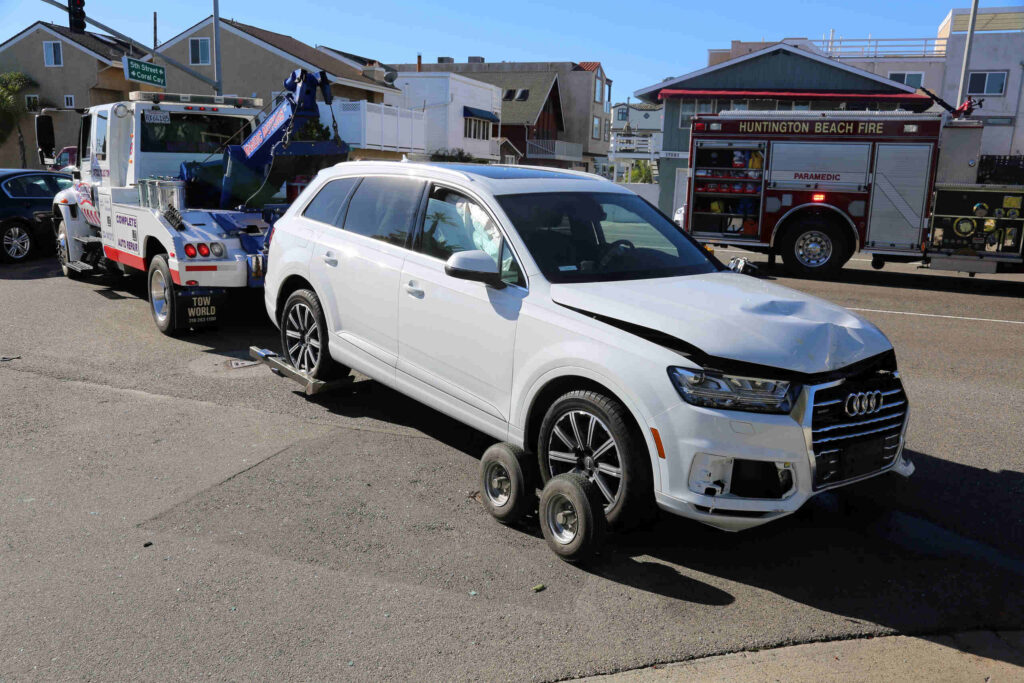
Key Takeaways: PIP and No Fault Insurance in FL
- PIP Pays First, Not Last: Your own policy covers early medical bills and lost income, but it rarely covers everything after a serious crash.
- Timing Protects Your Benefits: Getting initial treatment within 14 days keeps PIP available, and an emergency medical condition finding unlocks the full limit.
- The At-Fault Driver Still Answers for More: Economic losses beyond PIP, and pain and suffering for serious injuries, remain claims against the driver who caused the crash.
- Motorcyclists Play by Different Rules: PIP doesn't cover motorcycle riders, but riders generally don't have to meet the serious injury threshold either.
- Other Coverage Fills the Gap: Uninsured motorist coverage, medical payments coverage, and health insurance can pick up where PIP stops.
Is Florida a no-fault state?
Yes, Florida is a no-fault state; your own PIP pays first, up to $10,000, and you must get medical treatment within 14 days to use it. The key rules are:
- What PIP pays: PIP covers 80% of your medical bills and 60% of lost income, no matter who caused the crash.
- The emergency limit: Medical benefits stop at $2,500 unless a doctor finds you had an emergency medical condition.
- Pain and suffering: You can claim pain and suffering from the at-fault driver only if your injury meets Florida's serious injury threshold.
These rules apply to most drivers, passengers, and pedestrians hurt in Florida car crashes.
How Does PIP Insurance in Florida Work?
PIP insurance in Florida pays part of your medical bills and lost income after a crash, regardless of fault, up to a $10,000 limit. Every Florida vehicle owner must carry it, along with $10,000 in property damage liability coverage.
What PIP Pays and What It Doesn't
PIP pays 80% of your reasonable medical expenses and 60% of your lost income, and both come out of the same $10,000 limit. It can also pay for replacement services, such as help with chores you can't do while injured.
PIP doesn't pay for pain and suffering, the 20% of medical bills it leaves behind, or the 40% of lost wages it doesn't cover. After a serious crash, hospital and imaging bills alone can exhaust the limit within weeks, so knowing what comes next matters early.
The 14-Day Rule and the Emergency Medical Condition Limit
You must get initial medical treatment within 14 days of the crash to use Florida PIP benefits. Miss that window, and your insurer can deny the claim entirely, even if your injuries are real.
The amount available also depends on a medical finding. If a physician, dentist, physician assistant, or advanced practice registered nurse determines you had an emergency medical condition, you can access the full $10,000.
Without that finding, medical benefits stop at $2,500. Asking your treating provider to document the finding, if it applies, protects the full benefit.
Who PIP Insurance in Florida Covers
PIP insurance in Florida covers you, the relatives who live with you, and certain passengers and pedestrians. Your policy follows you as a driver or passenger in someone else's car, and it covers you as a pedestrian or cyclist struck by a car in Florida.
If you don't own a car, a policy held by a relative in your household may cover you. Passengers without their own PIP usually turn to the policy on the vehicle they rode in.
What Does No-Fault Mean for Fault and Lawsuits?
No-fault means PIP pays first, but it doesn't erase fault; the driver who caused the crash still answers for losses PIP doesn't cover. A few terms explain how that works:
- Tort exemption: Florida no-fault law shields the at-fault driver from paying losses PIP already covers. The driver remains responsible for losses beyond PIP.
- Economic damages: Losses with a price tag, such as medical bills and lost wages. You can seek economic losses beyond PIP from the at-fault driver.
- Serious injury threshold: The level of injury you must reach before claiming pain and suffering. Florida law defines it narrowly.
- Modified comparative fault: Florida's rule that reduces your recovery by your share of blame. Anyone found more than half at fault recovers nothing.
No-Fault Doesn't Mean No One Is at Fault
The at-fault driver still owes you for economic losses PIP leaves behind, even without a serious injury. For example, if your medical bills and lost wages total far more than your PIP pays, you can pursue the difference from the driver who caused the crash.
Fault also decides whether you can claim pain and suffering, which PIP never covers. Crash reports, video, and witness statements carry the same weight here as in any other state.
Pain and Suffering Requires a Serious Injury
You can claim pain and suffering from the at-fault driver only if your injury meets Florida's serious injury threshold. The threshold covers a significant and permanent loss of an important bodily function, a permanent injury within a reasonable degree of medical probability, or significant and permanent scarring or disfigurement.
Whether you meet it usually depends on your medical records and your doctors' opinions. Consistent treatment without long gaps gives you the strongest foundation.
Here's how Florida's system compares with states that use traditional at-fault insurance:
| Question | Florida No-Fault System | At-Fault States |
| Who Pays Your First Medical Bills? | Your own PIP, regardless of fault | The at-fault driver's insurer, after fault is decided |
| When Can You Claim Pain and Suffering? | Only if you meet the serious injury threshold | Generally after any injury caused by another driver |
| Does Fault Matter? | Yes, for losses beyond PIP | Yes, from the start |
| Required Injury Coverage | PIP required; bodily injury liability usually not | Bodily injury liability usually required |
When Does PIP Insurance in Florida Fall Short?
PIP insurance in Florida falls short whenever your losses exceed $10,000, your injuries happened on a motorcycle, or the at-fault driver carries little or no liability coverage. Each gap has its own fix.
Motorcyclists and PIP
PIP doesn't cover injuries you suffer while riding a motorcycle in Florida, even if you carry PIP on a car. Riders instead rely on the at-fault driver's liability coverage, their own uninsured motorist coverage, and medical payments or health insurance.
There's an upside, though. Because riders don't receive PIP benefits, they generally don't have to meet the serious injury threshold to claim pain and suffering from the driver who hit them. If you ride, checking your motorcycle policy for UM coverage shows how protected you really are.
Filling the Gap with UM, MedPay, and Health Insurance
Uninsured motorist (UM) coverage pays when the at-fault driver has no insurance or too little, and it can cover pain and suffering if you meet the threshold. Because Florida doesn't require most drivers to carry bodily injury liability coverage, UM often provides the main source of recovery after a serious crash.
Medical payments coverage can pay the 20% PIP leaves behind, and health insurance can cover treatment once PIP runs out.
How Can You Protect Your PIP Claim?
You can protect your PIP claim by acting within its deadlines and keeping clear records from the start. Several steps can help:
- Getting treatment within 14 days: Early care keeps PIP available and creates the medical record every later claim depends on.
- Asking about an emergency medical condition finding: The right documentation can raise your medical benefits from $2,500 to $10,000.
- Notifying your insurer promptly: Prompt notice starts the claim and keeps you within your policy's conditions.
- Tracking lost income: Pay stubs, employer letters, or tax records support the 60% wage benefit.
- Keeping every bill and receipt: Organized records make it easier to see when PIP runs out and other coverage should begin.
Bringing these materials to a consultation helps an attorney spot gaps in coverage before they become problems.
What Happens After You File a PIP Claim?
After you file, your insurer reviews your medical bills and may ask for more information. The insurer can request an independent medical examination by a doctor it chooses, or an examination under oath, which means answering questions on the record.
Florida generally requires PIP insurers to pay covered bills within 30 days of receiving proof of the claim. If payments slow down or stop, a lawyer can review whether the insurer followed the rules.
Why a Lawyer Matters When PIP Isn't Enough
A lawyer matters because the real value of a serious injury claim usually sits beyond PIP, in a claim against the at-fault driver or your UM coverage. An attorney builds the medical proof that shows you meet the serious injury threshold, identifies every policy that applies, and handles adjusters who may argue your treatment wasn't necessary.
Frequently Asked Questions About PIP and No Fault Accident Claims in FL
How long do I have to file a car accident lawsuit in Florida?
Florida gives you two years from the date of the crash to file a negligence lawsuit against the at-fault driver. Missing this deadline bars you from recovering compensation.
If a government vehicle or road defect played a role, written notice to the agency is due within three years. State agencies also require notice to the Department of Financial Services, while cities and counties receive notice directly.
Do seasonal residents need Florida PIP?
Yes, in many cases. If your car stays in Florida for more than 90 days in a year, Florida law generally requires you to carry Florida PIP and property damage liability coverage. Seasonal residents who skip that step may find themselves without coverage after a crash.
Does PIP cover me as a rideshare passenger?
Usually, your own PIP pays first if you have it. If you don't, Florida law requires rideshare companies to carry PIP coverage while a driver is logged into the app. Claims beyond PIP may involve the rideshare company's liability or UM coverage.
What if my insurer stops paying after an independent medical exam?
An insurer can cut off benefits if its chosen doctor says further treatment isn't needed, but that opinion isn't the final word. Your treating doctors' records may contradict it, and Florida requires a written demand before suing a PIP insurer.
Does PIP cover lost income if I'm self-employed?
Yes. PIP pays 60% of documented lost income, including self-employment income. Tax returns, invoices, and records of canceled work help show what you lost.
Talk with Roman Austin About What Comes After PIP
PIP gets you started, but it rarely finishes the job after a serious crash. Our firm looks past the first $10,000 to the claims that cover the rest: the at-fault driver's policy, your UM coverage, and every other source that applies.
If a careless driver hurt you anywhere in Florida, call Roman Austin at (727) 787-2500 for a free consultation.
John C. Austin
Partner and Trial Attorney
John C. Austin spent twelve years defending insurance companies, first at a Florida defense firm and then in-house at State Farm, before turning that experience toward injured clients. He holds the CPCU designation, earned by fewer than 4% of the insurance industry. A St. Petersburg native and University of Florida law graduate, he has handled thousands of personal injury claims and tried cases to verdict as first chair.
Author's Bio

